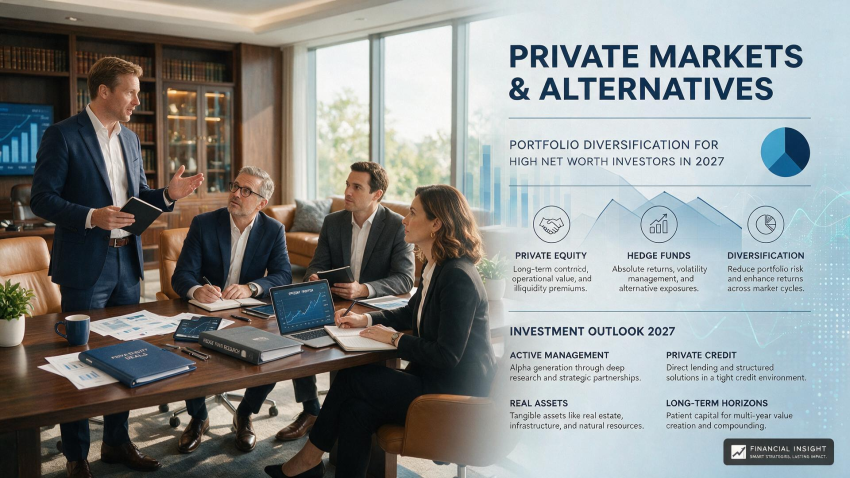
Why Alternatives Have Moved From the Periphery to the Core
For most of the past two decades, alternative investments occupied a specific and somewhat narrow place in the portfolios of wealthy families. They were the satellite holdings—the private equity fund that a friend recommended, the hedge fund that promised uncorrelated returns, the real estate partnership that offered a tax shelter. The core of the portfolio remained public stocks and bonds, and alternatives were a supplement that added a little diversification and a little complexity in roughly equal measure. That framing no longer holds. In 2027, alternatives have moved from the periphery to the core of how sophisticated investors think about building and preserving wealth, and the reasons are structural rather than fashionable.
The first reason is the changed behavior of public markets. The negative correlation between stocks and bonds that made the 60/40 portfolio so reliable for so long has become unstable, and in some periods it has flipped entirely. When inflation is the dominant risk, bonds stop cushioning equity losses and start contributing to them, because rising yields hurt both asset classes at the same time. The traditional diversification tools have become less effective at exactly the moment investors need them most, which has pushed allocators to look for return streams that are not simply a leveraged version of the public market. Alternative investment strategies—private credit, private equity, real assets, and certain hedge fund approaches—offer exposures that behave differently from the public markets because they are priced differently, held differently, and governed by different liquidity constraints.
The second reason is the maturation of the private markets themselves. Private equity and private credit are no longer niche asset classes accessible only to the largest institutional investors. The market has grown enormously, the managers have become more specialized, and the access points have multiplied. For high net worth investment strategies in 2027, the question is no longer whether to include alternatives but how to size them, how to select managers, and how to structure the liquidity profile so that the illiquidity premium is captured without exposing the household to forced sales during a downturn. The answer depends on the specific circumstances of each family, but the framework for thinking about it has become more standardized than it was a decade ago.
Private Equity: The Illiquidity Premium and Its Costs
Private equity investments are the most familiar alternative for wealthy investors, and they remain the largest allocation within the alternatives bucket for most family offices. The appeal is straightforward: private equity historically has delivered returns above public equity markets, and the illiquidity premium is the compensation for locking up capital for seven to ten years. The best managers have demonstrated the ability to create value through operational improvements, strategic guidance, and the kind of active ownership that is impossible in a public company with dispersed shareholders. For investors who can tolerate the lockup and who have access to top-tier managers, private equity has been a reliable source of outperformance over long horizons.
The costs, however, are substantial and often underestimated. The standard fee structure of two percent of assets plus twenty percent of profits creates a significant drag on returns, and the gross return must be high enough to overcome that drag before the investor sees any benefit. The dispersion between top-quartile and bottom-quartile private equity managers is enormous—far wider than in public markets—which means manager selection is the single most important determinant of outcomes. An investor who gains access to a mediocre private equity fund would often have been better off in a low-cost public index fund, and the difficulty of identifying the top managers in advance is the central challenge of the asset class.
The other cost of private equity is the cash flow profile. Capital is not invested all at once; it is drawn down over several years as the manager identifies opportunities, which means the investor must maintain liquidity to meet capital calls even while the committed capital sits idle. During the 2022 drawdown, many investors discovered that their private equity commitments had created a liquidity mismatch: they had committed capital they could not access while the public markets were falling and their other assets were declining. The managers who navigated that period well were the ones who had sized their private equity allocations relative to their total liquid assets, not relative to their total net worth. The alternative asset management approach that works best treats the committed but uncalled capital as a liability that must be funded, not as an asset that can be ignored until the capital call arrives.
The access question has also changed. The traditional route into private equity was through a fund with a minimum investment of several million dollars, which limited the asset class to the very wealthy. That is still true for the top-tier funds, but the market has developed feeder funds, interval funds, and other structures that allow smaller investors to participate. The trade-off is that the lower minimums often come with higher fees, less favorable terms, and reduced access to the best managers. For investors with $1 million to $5 million in investable assets, the question is whether the additional diversification and potential return are worth the fees and the complexity. For investors with $10 million or more, the traditional fund structure is usually the better path, provided the allocation is sized appropriately within the broader portfolio.
Hedge Funds: The Search for Genuine Uncorrelated Return
Hedge fund investments occupy a different role in the portfolio than private equity. Where private equity is about capturing the illiquidity premium and generating long-term growth, hedge funds are primarily about diversification and risk management. The best hedge funds generate returns that are not correlated with the public markets, which means they provide ballast during periods when stocks and bonds are falling together. That uncorrelated return is valuable precisely because the traditional sources of diversification have become less reliable, and the investors who have maintained a meaningful hedge fund allocation through the recent volatility have generally experienced smaller drawdowns than those who relied on a simple stock-bond mix.
The hedge fund landscape, however, is far more heterogeneous than the label suggests. The category includes long-short equity funds, global macro funds, event-driven funds, relative value funds, and quantitative strategies that have very little in common with each other. The correlation between different hedge fund strategies can be low, which means a portfolio of several uncorrelated hedge funds can achieve a level of diversification that no single fund can provide. But the fees are high—typically two and twenty, though some funds have moved to lower or performance-only structures—and the dispersion between the best and worst managers is as wide as it is in private equity. The hedge fund investments that make sense for a high net worth portfolio are the ones where the manager has a clearly articulated edge, a track record that demonstrates genuine skill rather than leveraged beta, and a fee structure that aligns incentives with the investor’s goals.
The liquidity profile of hedge funds is also different from private equity. Most hedge funds offer quarterly or annual redemption windows, which provides more flexibility than the ten-year lockup of a private equity fund, but the redemption rights can be suspended during periods of market stress. The investors who experienced the 2008 crisis or the March 2020 volatility learned that the liquidity promised in the fund documents is not always available when it is most needed. The prudent approach is to treat the hedge fund allocation as a semi-liquid component of the portfolio, accessible in normal conditions but not counted on during a crisis. That framing prevents the kind of liquidity mismatch that forces investors to sell other assets at depressed prices to meet their cash needs.
Private Credit and Real Assets: The Middle Ground
Between the long lockups of private equity and the semi-liquid hedge fund structure sits a category that has grown enormously in recent years: private credit. Private credit funds lend to middle-market companies that are too small for the public bond markets or that need financing structures that banks are no longer willing to provide. The yields are higher than comparable public bonds, and the lenders are compensated for the illiquidity and the underwriting work that goes into each loan. For investors seeking income without the interest rate risk of long-duration public bonds, private credit has become an attractive alternative, and the asset class has attracted hundreds of billions of dollars from institutional and high net worth investors.
The risk in private credit is not the interest rate risk that dominates public bond investing. It is credit risk—the risk that the borrowers will not repay—and liquidity risk, because private credit loans are not traded and cannot be sold quickly if the investor needs cash. The asset class performed well during the recent period of higher rates because the loans are typically floating rate, which means the yields rose as the benchmark rate rose. But the credit cycle does not run in a straight line, and the investors who are entering private credit now need to be confident that the underwriting standards of their chosen managers are strong enough to withstand a downturn. The private wealth management approach that works best for private credit is to diversify across managers and vintages, rather than concentrating the allocation in a single fund or a single year of originations.
Real assets—real estate, infrastructure, commodities, and natural resources—provide a different kind of diversification. These investments have historically offered some protection against inflation, because the underlying assets are physical and their values tend to rise with the general price level. Infrastructure investments, in particular, have attracted significant interest because they offer long-duration, inflation-linked cash flows that are well-suited to matching long-term liabilities. Data centers have become a particularly active segment, driven by the demand for AI infrastructure, and the investors who positioned themselves in that sector early have captured substantial returns. The risk is that the demand is concentrated in a small number of hyperscale tenants, and the investors who are underwriting these assets need to be confident that the tenant concentration is manageable and that the pricing power will persist.
The common thread across private credit and real assets is that they offer exposures that are genuinely different from public stocks and bonds, at a cost of illiquidity and complexity. For investors who can tolerate the lockups and who have the scale to access institutional-quality managers, these asset classes can improve the risk-adjusted return profile of the overall portfolio. For investors who cannot tolerate the illiquidity or who lack the scale to diversify across managers, the simpler public market alternatives may be more appropriate. The high net worth investment strategies that work best are the ones that match the asset class to the investor’s actual liquidity needs, not the ones that chase the highest headline return regardless of the constraints.
The Practical Questions Every Investor Should Ask
The decision to allocate to alternatives is not a single decision but a series of them. The first question is how much to allocate, and the answer depends on the investor’s total net worth, the liquidity of the other assets, and the time horizon. A common guideline is that the alternatives allocation should not exceed the amount the investor can afford to leave untouched for the full lockup period, even in a worst-case scenario. For a household with $10 million in investable assets and $2 million in annual spending, a twenty percent allocation to alternatives would leave $8 million in liquid assets, which is roughly four years of spending. That is a reasonable buffer, but it is not generous, and the investor should stress-test the allocation against a scenario in which the public markets fall sharply at the same time that capital calls come due.
The second question is how to select managers. The dispersion between top and bottom performers in private markets is so wide that manager selection dominates every other decision. The best approach is to look for managers with a clear, repeatable investment process, a track record that covers at least one full market cycle, and a team that has stayed together through that cycle. Past performance is not a guarantee of future results, but a manager who has generated strong returns across different market environments is more likely to be skilled than lucky. The third question is how to structure the allocation across vintages. Because private equity and private credit funds draw down capital over several years, committing to a single fund in a single year concentrates the portfolio in a particular market environment. The investors who commit to a series of funds over several years—a process known as vintage diversification—reduce the risk that a single bad year will dominate the portfolio’s returns.
The final question is the one that gets the least attention: what is the exit strategy? Alternatives are illiquid by design, and the exit from a private equity or private credit fund is typically a sale of the underlying assets rather than a redemption of the investor’s shares. The timing of that sale is controlled by the manager, not the investor, and it may not coincide with the investor’s own liquidity needs. The investors who plan for this ahead of time, either by maintaining sufficient liquidity elsewhere or by using secondary market sales when necessary, are the ones who avoid being forced into unfavorable exits. The accredited investor opportunities that are worth pursuing are the ones that come with a clear understanding of the exit timeline and a realistic plan for managing the illiquidity.
Building a Diversified Alternative Portfolio That Survives a Downturn
The most important lesson from recent market cycles is that alternatives are not a substitute for liquidity. They are a complement to it. The investors who fared best through the 2022 drawdown were the ones who had maintained a substantial reserve of liquid assets, who had not overcommitted to illiquid strategies, and who had diversified across managers and vintages rather than concentrating their alternatives allocation in a single fund. The investors who struggled were the ones who had treated the illiquidity premium as free money, without accounting for the possibility that they might need the capital at exactly the wrong moment.
The second lesson is that the diversification benefit of alternatives depends on genuine exposure differentiation. A portfolio that holds three private equity funds, two private credit funds, and a hedge fund has some diversification, but it is not the same as a portfolio that spans private equity, private credit, real assets, and uncorrelated hedge fund strategies. The goal is not to own every asset class but to own exposures that respond differently to the same economic shocks. The third lesson is that the fee drag matters. A portfolio of high-fee alternatives can underperform a simple public market portfolio if the manager selection is mediocre, and the investors who have succeeded with alternatives are the ones who have been selective rather than indiscriminate.
The final lesson is that alternatives require more active monitoring than public market investments. The quarterly reports, the capital calls, the distribution notices, and the annual valuations all require attention, and the investor who neglects them may discover that the allocation has drifted far from its target. The alternative investment strategies that produce results are the ones that are reviewed regularly, rebalanced when necessary, and managed with the same discipline as the public market portfolio. The alternative asset class is not a passive hold. It is an active commitment, and the investors who treat it that way are the ones who capture the benefits without being blindsided by the costs. The landscape in 2027 offers more opportunities than ever before, but it also demands more sophistication. The investors who bring that sophistication to the table will find that alternatives can be a genuinely valuable component of a diversified, long-term wealth management strategy.