2026 Is a Year Where Home Equity Is Expensive to Tap and Easy to Mismanage
The idea of using home equity to buy an investment property is one of the most seductive concepts in real estate. You already own an asset that has appreciated, you have a chunk of untapped value sitting there, and instead of letting it sit idle you can leverage it into another property that generates income and appreciation of its own. On paper, it is an elegant way to scale a portfolio without saving up another down payment. In practice, it is a strategy that has enriched some investors and ruined others, and the difference between the two outcomes is rarely about the property they bought. It is about whether they understood the financing they used to buy it.
The 2026 environment makes that distinction more consequential than it was during the low-rate years. The Federal Reserve has held rates higher for longer than most forecasters expected, and the home equity lending market has adjusted accordingly. HELOC rates are in the high single digits for most borrowers, home equity loans are pricing similarly, and cash-out refinances have become more expensive because the new first mortgage replaces a low-rate loan that the borrower may have locked in years ago. The Home Equity Investment Strategies that worked when rates were at three percent no longer work when the cost of tapping the equity is seven or eight percent, and the investors who ignore that shift are the ones who discover that the income from the new property does not cover the cost of the borrowing.
HELOC and the Flexibility That Cuts Both Ways
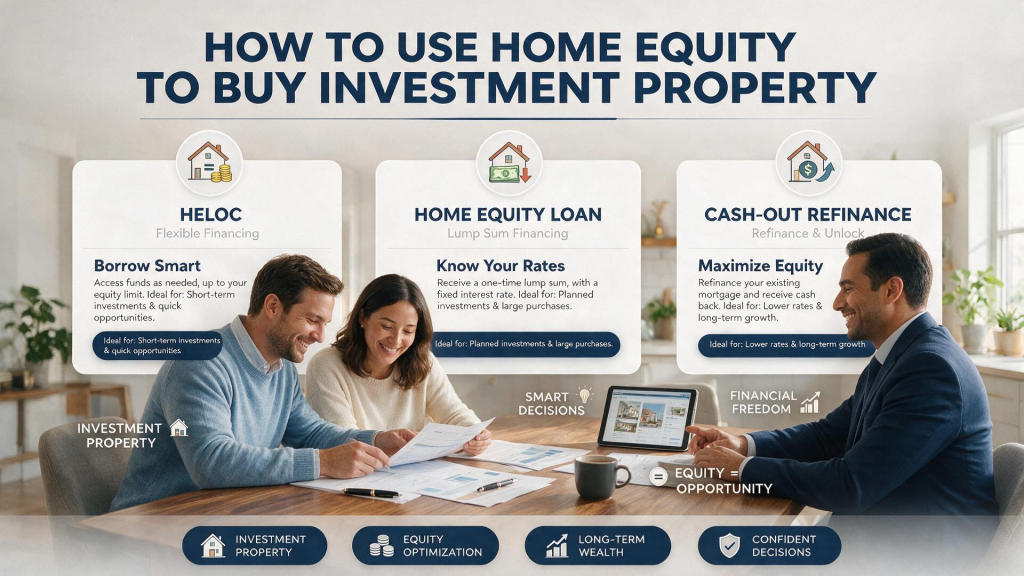
The HELOC for Investment Property is the most flexible of the three options, and it is also the one that requires the most discipline. A home equity line of credit is a revolving credit line secured by your home, and you can draw from it as needed, repay it, and draw again, up to the credit limit. The rate is typically variable and tied to the prime rate, which means the interest you pay will rise and fall with the Federal Reserve’s decisions. In 2026, HELOC rates for well-qualified borrowers are running in the 7.5 to 9.5 percent range, which is meaningfully higher than the rates that prevailed a few years ago.
The flexibility is the appeal. If you find a property that needs a quick close, the HELOC provides the capital without the underwriting delay of a new mortgage. If the renovation costs more than expected, the HELOC can cover the overrun. If the property is vacant for a few months, the HELOC can carry the mortgage payments until a tenant is found. The problem is that the flexibility can become a trap. The borrower who draws on the HELOC for the down payment, then draws again for the renovation, then draws again for the carrying costs can end up with a credit line that is fully drawn and a monthly payment that is larger than the rental income. The Real Estate Leverage Strategies that work treat the HELOC as a bridge, not as a permanent source of capital, and they have a plan for paying it down before the variable rate resets higher.
The other issue with the HELOC is the lender’s right to freeze or reduce the line. During the 2008 financial crisis, many lenders froze HELOCs without warning, leaving borrowers unable to access the capital they had been counting on. The same risk exists in any environment where the lender’s assessment of the collateral value declines. The Use Home Equity to Buy Investment Property strategy that survives the cycle assumes that the HELOC may not be available when it is needed, and it maintains a backup source of capital. The investors who rely on a single credit line are the ones who are exposed to the lender’s decisions rather than to their own.
Home Equity Loans and the Fixed Rate That Provides Certainty
The Home Equity Loan for Investment Property is the fixed-rate alternative to the HELOC. It is a lump-sum loan secured by your home, with a fixed interest rate and a fixed repayment schedule, typically five to thirty years. The rate in 2026 is comparable to the HELOC rate for the initial period, but the fixed rate means the payment will not change if the Federal Reserve raises rates. For an investor who is using the proceeds to buy a rental property and who wants to match the cost of the borrowing to the income from the property, the predictability of the fixed rate is a meaningful advantage.
The trade-off is the lack of flexibility. The home equity loan is disbursed in a single lump sum, which means you pay interest on the full amount from the day it is funded, even if you do not need all the capital immediately. If the renovation comes in under budget or the property is purchased for less than expected, the extra capital sits in your checking account earning a low rate while you pay the loan rate on it. The Investment Property Mortgage Rates on a home equity loan are also typically higher than the rates on a first mortgage, because the lender is in the second position and the risk is higher. The borrower who is using a home equity loan should compare the rate to the rate on a DSCR loan or a conventional investment property mortgage, because the home equity loan may not be the cheapest option even after accounting for the closing costs.
The other consideration with the home equity loan is the impact on the borrower’s overall debt profile. The loan is secured by the primary residence, which means a default can result in the loss of the home. The Rental Property Financing that uses the primary residence as collateral is inherently riskier than the financing that uses the investment property as collateral, because the consequences of a default are more severe. The investors who use a home equity loan to buy an investment property are betting that the rental income will cover the loan payment and that the property will not sit vacant for an extended period. That bet can be reasonable, but it has to be sized so that a vacancy or a repair does not create a cash flow crisis that threatens the home.
Cash-Out Refinance and the Rate Reset That Most Borrowers Underestimate
The Cash Out Refinance Investment Property is the third option, and it is the one that has become the most expensive in 2026. A cash-out refinance replaces your existing first mortgage with a new, larger mortgage and gives you the difference in cash. The appeal is that the new mortgage is a first lien, which means the rate is lower than a second lien, and the interest may be tax-deductible if the funds are used to buy, build, or substantially improve the property. But the rate on the new mortgage applies to the entire balance, not just the cash-out portion, which means the borrower who locked in a three percent mortgage a few years ago will be replacing that rate with a rate in the six to seven percent range on the full loan amount.
The math on that replacement is the reason cash-out refinances have become less attractive. A borrower with a $300,000 mortgage at 3.5 percent is paying roughly $1,347 per month in principal and interest. If they refinance to a $400,000 mortgage at 6.5 percent to extract $100,000, the new payment is roughly $2,528 per month, an increase of more than $1,100. The $100,000 of cash-out capital is not free; it costs the borrower the difference in the monthly payment over the life of the new loan, plus the closing costs on the refinance. The Home Equity Investment Strategies that work compare the cost of the cash-out to the return on the property that the capital is buying, and they only proceed if the spread is large enough to justify the risk.
The tax treatment of the cash-out refinance is also more complicated than most borrowers realize. The interest on the portion of the new mortgage that replaces the old mortgage is deductible under the same rules that applied to the original loan, but the interest on the cash-out portion is only deductible if the funds are used for a qualified purpose. If the funds are used to buy an investment property, the interest may be deductible as an investment expense rather than as mortgage interest, which means the deduction is subject to different limits and different rules. The Use Home Equity to Buy Investment Property strategy that works consults a tax advisor before the refinance, because the tax treatment can change the after-tax cost of the borrowing by a meaningful amount.
The Debt Service Coverage That Determines Whether the Strategy Is Sound
Regardless of which financing option the investor chooses, the key question is whether the income from the new property covers the cost of the borrowing. The debt service coverage ratio is the property’s net operating income divided by the annual debt service, and a ratio of 1.0 means the income exactly covers the payment. Most lenders want a ratio of at least 1.2, and the investors who are using home equity to buy an investment property should want a ratio that leaves room for vacancy, repairs, and the inevitable surprises. The Rental Property Financing that works is the one where the property generates enough income to cover the debt service with a margin, not the one where the investor is relying on appreciation to make the numbers work.
The other metric that matters is the cash-on-cash return, which is the annual cash flow divided by the cash invested. If the investor is using home equity to fund the down payment, the cash invested is the equity that was extracted, and the cash-on-cash return measures the return on that specific capital. A property that produces $8,000 in annual cash flow on a $100,000 home equity extraction has a cash-on-cash return of 8 percent, which is meaningful if the cost of the home equity borrowing is 7 percent. The spread between the return on the property and the cost of the borrowing is the margin that compensates the investor for the risk, and the Real Estate Leverage Strategies that work are the ones where that spread is positive and large enough to absorb a decline in rent or an increase in the borrowing cost.
Building a Leverage Plan That Survives the Rate Cycle
The most important lesson from the past several years is that the cost of leverage is not fixed. The HELOC rate can reset higher, the home equity loan can mature and need to be refinanced at a higher rate, and the cash-out refinance locks in the current rate for the life of the loan but at a cost that may be higher than the borrower anticipated. The Investment Property Mortgage Rates that the investor can access depend on the borrower’s credit, the property type, and the lender’s appetite, and those variables change over time. The investors who do well are the ones who build a leverage plan that assumes the cost of capital will rise, and who size the borrowing so that the plan still works if it does.
The other lesson is that the home equity strategy is not a substitute for the property-level analysis. The fact that the capital is available does not mean the property is a good investment. The investor who buys a property because the HELOC was there is the one who ends up with a property that does not cash flow, a credit line that is fully drawn, and a primary residence that is at risk. The Use Home Equity to Buy Investment Property strategy that works starts with the property analysis and then looks for the cheapest way to finance it, not the other way around.
The final consideration is the one that no rate table captures: the investor’s own tolerance for the risk that the primary residence is carrying. A borrower who uses the home equity to buy an investment property is putting the family home on the line for the sake of the portfolio. That decision may be entirely reasonable for an investor with a stable income, substantial reserves, and a clear understanding of the downside. It is not reasonable for an investor who is stretching to buy the first property and who has no cushion if the rent does not arrive. The Home Equity Investment Strategies that work are the ones that match the leverage to the investor’s actual financial situation, and that recognize that the cheapest capital is not always the safest capital.